A higher renewal premium can be frustrating, especially when you have not filed a claim. Insurance pricing is shaped by more than one customer’s history. Carriers also consider the expected cost of future claims, repair and rebuilding expenses, weather losses, liability trends, and the characteristics of each home, vehicle, household, or business.
Not every customer, carrier, or line of insurance is experiencing the same change. Your results may differ based on location, coverage, deductibles, claims history, discounts, underwriting, and many other factors. Still, several broad cost pressures help explain why many consumers are seeing higher prices in 2026.
Why premiums can change even when you have not filed a claim
Insurance works by pooling risk. A carrier estimates how often claims may occur and how much those claims may cost across a group of policyholders. When the projected cost of repairs, rebuilding, medical care, litigation, or catastrophe losses rises, the rates needed to support that risk can rise as well.
Your own record remains important, but it is only one part of the calculation. Territory, vehicle or property characteristics, coverage limits, deductible choices, and the carrier’s current underwriting approach can also affect the final premium.
1. Vehicles cost more to repair and replace
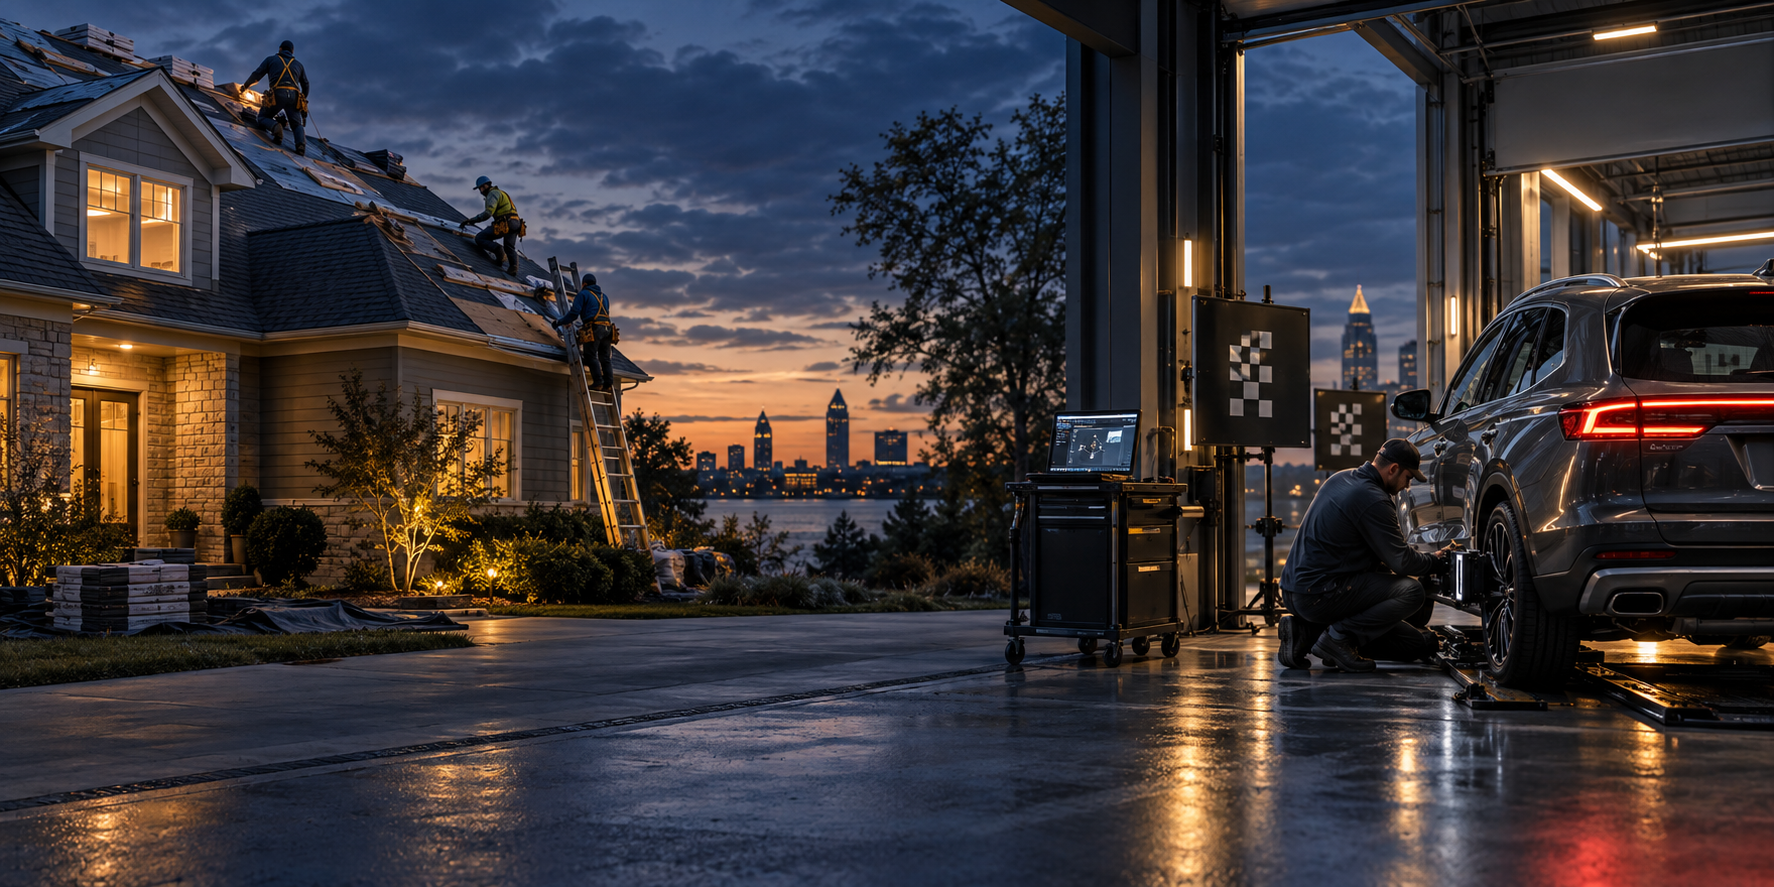
Modern vehicles are safer and more capable, but the technology behind those improvements can make even a routine repair more involved. Bumpers, mirrors, windshields, and body panels may contain cameras, radar, sensors, or other advanced driver-assistance equipment. After parts are replaced, those systems may need specialized diagnostics and calibration.
- Parts, paint, towing, storage, and skilled labor can cost more
- Sensor and camera calibration can add steps to a repair
- Longer repair times can increase rental-car expenses
- Higher new and used vehicle values can increase total-loss costs
These trends can affect both personal auto and commercial auto pricing, although the impact varies by driver, vehicle, use, location, and carrier.
2. Homes cost more to rebuild
Home insurance is generally concerned with the cost to repair or rebuild a damaged home, not simply its real-estate market value. Construction labor, roofing, lumber, fixtures, mechanical systems, debris removal, and updated building-code requirements can all influence a claim.
After a major storm, many property owners may need contractors and materials at the same time. That surge in demand can add further pressure to rebuilding costs. Keeping the dwelling limit and other property limits current is important, even when a higher limit affects the premium.
3. Severe weather and catastrophe losses affect the broader market
Hail, wind, tornadoes, hurricanes, wildfires, flooding, and other severe events can produce a large number of claims in a short period. The mix of hazards differs by region, but catastrophe losses can influence insurers and reinsurers well beyond the location of a single event.
In Ohio, severe thunderstorms, damaging wind, hail, winter weather, and localized flooding are among the risks carriers evaluate. That does not mean every Ohio property will see the same rate change. Construction, roof age, protection features, territory, prior losses, and each carrier’s experience still matter.
4. Reinsurance affects what insurers pay for protection
Reinsurance is often described as insurance for insurance companies. It helps primary insurers manage large or unusually concentrated losses. When reinsurance becomes more expensive or less available for certain risks, it can add pressure to the overall cost of providing coverage.
Customers do not purchase reinsurance directly, but its cost and availability can influence carrier capacity, underwriting decisions, and pricing.
5. Liability claims are becoming more expensive
Liability coverage may respond when an insured person or business is legally responsible for injury or property damage. The cost of medical treatment, vehicle and property repairs, legal defense, settlements, and court awards can increase the severity of those claims.
This matters for auto, homeowners, umbrella, landlord, and business policies. Higher liability limits may still be appropriate even when they cost more, particularly when assets, income, passengers, tenants, customers, or business operations create meaningful exposure.
6. Inflation and broader economic pressures still matter
Insurance claims ultimately pay for real goods and services. When wages, replacement parts, construction materials, medical care, equipment, and professional services cost more, the amount required to settle a claim can rise. Interest rates, capital costs, regulation, and market conditions may also affect insurers differently over time.
Does a higher premium mean every carrier will price you the same?
No. Insurance companies have different rating plans, discounts, coverage options, underwriting appetites, and loss experience. One carrier may be comfortable with a particular home, vehicle, household, rental property, or business while another may price it differently or decline it altogether.
That is one reason an independent agency can be useful. Graziano & Lorince can review available carrier options and help you compare more than the premium alone. Limits, deductibles, endorsements, exclusions, service, and overall fit all deserve attention.
What can you do before your next renewal?
- Review coverage limits. Confirm that home replacement estimates, liability limits, scheduled property, and other values still reflect your needs.
- Compare deductible options. A higher deductible may reduce premium, but choose an amount you could reasonably pay after a loss.
- Confirm discounts and bundling. Ask whether home and auto bundling, protective devices, safe-driving programs, payment choices, or other discounts are available and appropriate.
- Reduce avoidable risk. Maintain roofs, plumbing, electrical systems, vehicles, and business equipment. Consider alarms, water-leak detection, defensive driving, or other practical safeguards.
- Keep policy information accurate. Review drivers, vehicles, mileage, property features, business operations, and contact information.
- Compare available carrier options. Different carriers may view the same risk differently, subject to eligibility and underwriting.
Be cautious about reducing coverage simply to lower the price. A less expensive policy may leave a larger deductible, a lower limit, or a missing protection that matters when a claim occurs. A thoughtful review should consider both cost and the financial risk you would keep.
A coverage review can help put the increase in context
If your renewal has changed, bring the current declarations pages and renewal offer to the conversation. We can help explain what changed, review available discounts and deductible options, and compare eligible carrier choices when appropriate.
Coverage availability, eligibility, and pricing vary by carrier and underwriting. This article provides general educational information and is not a promise of coverage or savings.